Most people applying for a home loan have heard of CCRIS. Fewer have actually looked at one, and fewer still know what the numbers on it mean.
That's a problem, because CCRIS is one of the first things a bank checks — often before it even looks closely at your income. A clean CCRIS report can move an application through in weeks. A report with a few unexplained late payments can stall it, or sink it, regardless of how much you earn.
Here's what's actually in the report, how to read it, and what to do if yours isn't as clean as you'd like.
What CCRIS Actually Is
CCRIS stands for the Central Credit Reference Information System. It's run by Bank Negara Malaysia, not by any individual bank, and it isn't a credit score — it's raw data. There's no pass or fail number attached to it. BNM collects repayment information from every participating financial institution and compiles it into one report covering your credit history for the past 12 months.
This is a useful distinction. Companies like CTOS and Experian are private credit reporting agencies that take CCRIS data and combine it with other information to produce a score. CCRIS itself is just the underlying record — which is exactly why it's worth understanding on its own terms, rather than only worrying about a score you can't see the working behind.
What's Actually in the Report
Your credit facilities
Every loan, credit card, and financing facility you hold with a participating institution — home loans, car loans, personal loans, credit cards, hire purchase, business financing. For each one, the report shows the credit limit, the outstanding balance, and the instalment amount.
Conduct of account for the last 12 months
This is the section that matters most, and the one people find hardest to read. For each facility, there's a row of numbers, one per month, showing your repayment conduct:
| Code | Meaning |
|---|---|
| 0 | Payment made on time |
| 1 | One month in arrears |
| 2 | Two months in arrears |
| 3 or higher | Three or more months in arrears — treated as a serious red flag by most lenders |
A row that reads "0 0 0 0 0 0 0 0 0 0 0 0" is what every lender wants to see. A row with scattered 1s is noticed but often forgivable if it's old and isolated. A row with 2s and 3s, especially recent ones, is where applications start getting declined.
Special Attention Accounts
A Special Attention Account, often shown as SAA, flags a facility that a bank is monitoring more closely than normal — typically because of a pattern of late payments, a restructuring arrangement, or early signs of financial distress. It doesn't necessarily mean the account is in default, but lenders treat even one SAA entry as a reason to look harder at the rest of the application.
Legal status
If a bank has taken legal action over an unpaid facility, it shows here. This is the most serious entry on the report and makes new financing very difficult to obtain until it's resolved.
Application history
Every credit application you've made in the past 12 months is recorded, whether it was approved, rejected, or withdrawn — including applications with other banks. A cluster of recent applications reads to a lender as financial pressure, even if every application was for a good reason.
How to Get Your Report
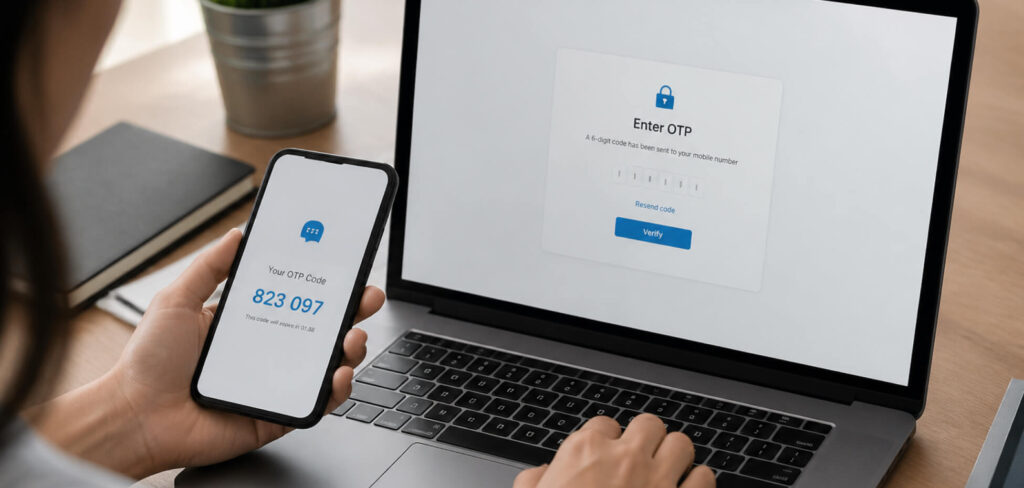
The eCCRIS portal, run directly by Bank Negara Malaysia, is the official free channel. Registration involves a one-off RM1 verification transfer from your own internet banking account, refunded within two working days, followed by a 6-digit OTP sent to your registered mobile number and email. Once registered, you can view, download, or print your report at any time.
There's no cost to check your own report, and no limit on how often you can look.
What Actually Counts Against You
Recent arrears matter more than old ones
A late payment from three years ago carries far less weight than one from last month. Most lenders focus heavily on the most recent two to three months of conduct — a single late payment there can outweigh a clean record stretching back years.
Credit utilisation, not just repayment
Even with a perfect "0 0 0" conduct record, running your credit cards consistently close to their limit signals financial strain to a lender. Keeping balances comfortably below the limit for a few months before applying makes a genuine difference.
Multiple recent applications
Applying to several banks in a short window doesn't just risk multiple rejections stacking up — the applications themselves are visible to every subsequent lender, and a cluster of them reads as financial pressure even before any decision comes back.
An empty report isn't automatically a good thing
No credit history at all can be almost as unhelpful as a patchy one, because the bank has nothing to assess. If you've never held a credit facility, opening one modest card and paying it off in full for a few months before a major application gives a lender something concrete to work with.
How to Fix a Patchy CCRIS Before You Apply
- Settle small arrears completely, not partially. A facility that's fully up to date reports as 0 the following month; a partial catch-up doesn't.
- Give it time to update. Updates from financial institutions are reflected in CCRIS on the 10th of the following month, subject to public holidays. Plan ahead rather than settling something the week before you apply.
- Fix a mismatched billing cycle. If your salary lands after your card's due date every month, that's a structural reason for recurring late payments — most banks will shift your billing date on request.
- Avoid new applications in the run-up to a major one. Hold off on new cards or personal financing for a few months before applying for a home loan.
- Bring down utilisation before you apply, not after. Three months of comfortably low balances reads far better than a single payment made the week of the application.
Common Mistakes
- Assuming a rejection disappears quickly. It stays visible in your application history for a full 12 months, even once the underlying facility is resolved.
- Believing CCRIS can be "cleared" for a fee. It can't. CCRIS is a factual record maintained by Bank Negara — anyone offering to erase or fix entries for payment is not offering a real service.
- Confusing CCRIS with a credit score. CCRIS has no score attached. If you're also checking a CTOS or similar report, treat the two as related but separate pieces of information.
Frequently Asked Questions
What does a 1 or 2 mean on my CCRIS report?
These are arrears codes showing how many months behind you were on a specific facility. A 1 means one month in arrears, a 2 means two months, and so on. A 0 means the payment was made on time. Most lenders treat 3 or higher as a serious concern, particularly if it appears in the most recent months.
What is a Special Attention Account?
A facility a bank is monitoring more closely than usual, often due to a pattern of late payments or an early sign of financial distress. It's a flag rather than a default, but lenders generally treat even one SAA entry as reason to review the rest of an application carefully.
How do I check my CCRIS report for free?
Through the eCCRIS portal, run directly by Bank Negara Malaysia. Registration requires a one-off RM1 verification transfer, which is refunded, and an OTP sent to your phone and email. Once registered, you can view your report at any time at no cost.
Can I remove a late payment from my CCRIS record?
Not directly, and not for a fee — CCRIS is a factual record of what happened. What you can do is bring the facility fully up to date and let clean conduct accumulate from that point, since recent conduct carries far more weight with lenders than older entries.
Does applying to multiple banks hurt my CCRIS?
Every application is recorded and visible to subsequent lenders for 12 months, whether it was approved or not. Several applications in a short window can read as financial pressure, which is why assessing your profile before applying, rather than applying broadly, tends to produce better outcomes.
How long does a settled debt take to update on CCRIS?
Updates from financial institutions are reflected in CCRIS on the 10th of the following month, subject to public holidays. If you're settling something ahead of a loan application, it's worth doing well in advance rather than the week before.
Not sure how your CCRIS report reads to a bank?
We work with 12+ bank partners and can help you interpret your report and time your application right. Email us or get in touch for a personalised assessment.