
Our Services
SME Loan Application Services in Malaysia
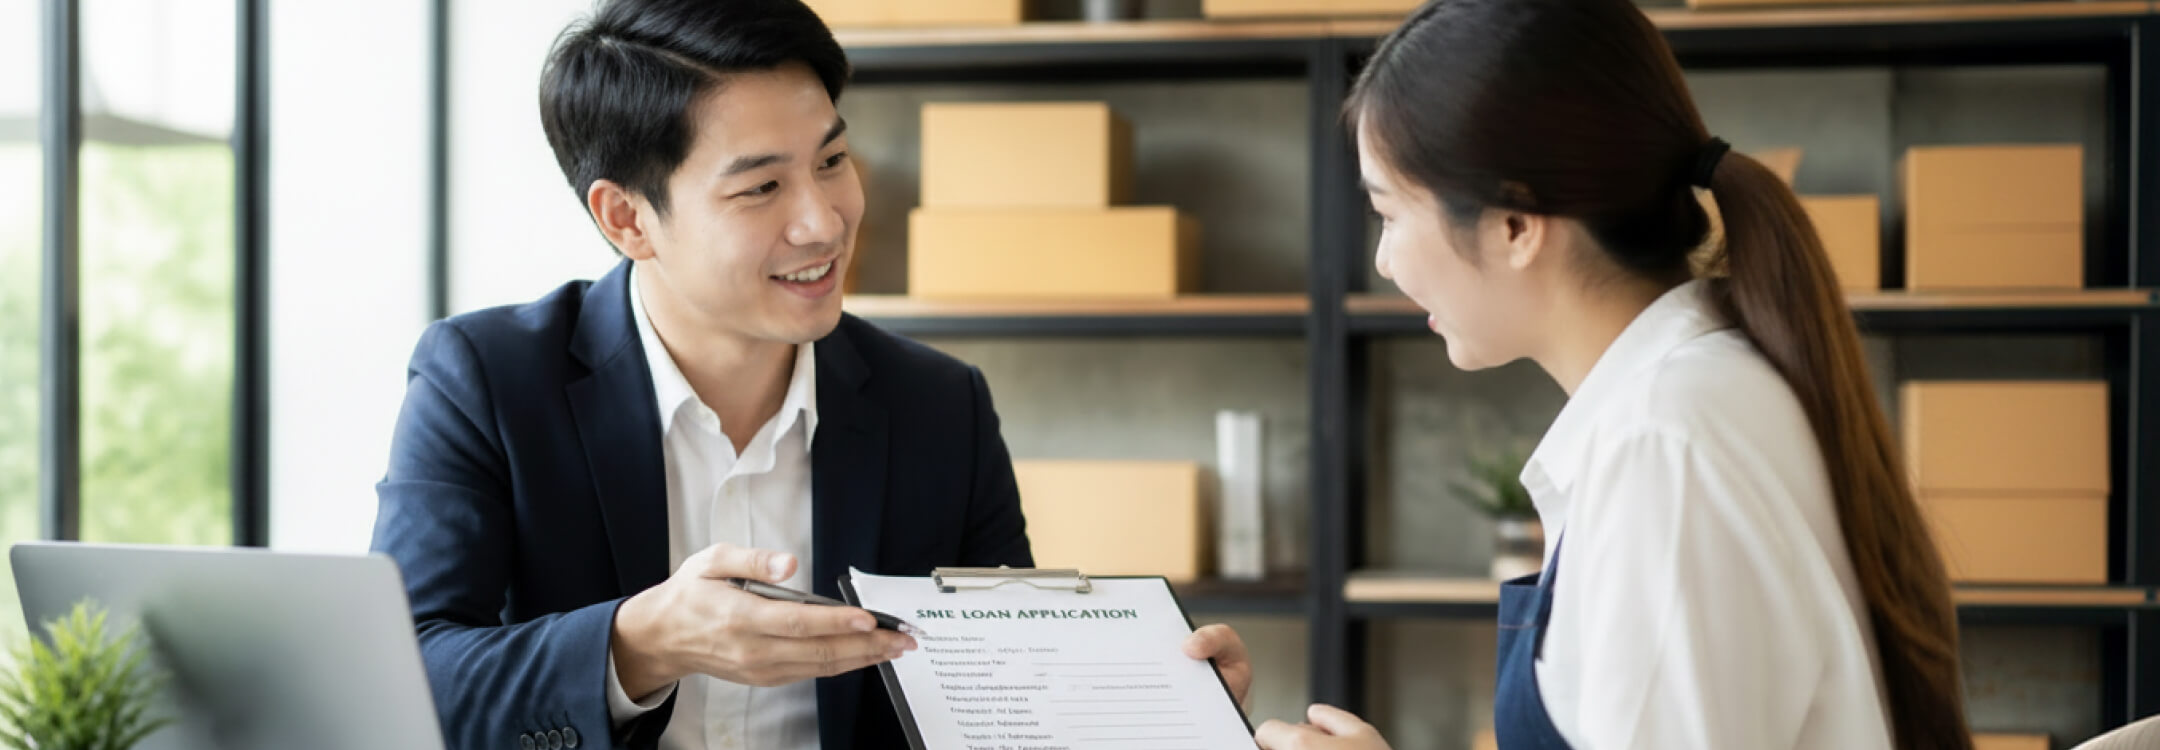
Business financing for small and medium enterprises
Business lending in Malaysia works differently from personal financing. Banks assess your company's cash flow, trading history, director profiles and sector — and each institution has its own appetite for risk and for particular industries.
We offer comprehensive guidance on SME loan applications, assisting with the necessary documentation — proof of identity, business financial statements, business plans and more — and matching your company with lenders whose criteria genuinely fit your profile.
The difference between an approval and a rejection is frequently not the strength of the business. It is whether the application was presented to a bank that lends to businesses like yours, in the format that bank expects.
Why SME Loan Applications Get Rejected

Bad credit scoring or lack of credit history
Directors' personal CCRIS records affect the company's application. A business with no borrowing history can be as difficult to assess as one with a poor record, because the bank has nothing to evaluate.

Limited collateral
Businesses without property or substantial assets to pledge fall into a higher risk group. This does not make financing impossible, but it narrows which lenders and which facility types are realistic.

Poor evidence of strong cash flow
Banks want to see consistent turnover across six to twelve months of company bank statements. Irregular deposits, frequent overdrawn balances, or heavy reliance on a single customer all raise questions.

High debt utilisation rate
If existing facilities are consistently drawn to their limit, banks read it as strain rather than growth — regardless of whether the business is profitable.

Incomplete application
The most avoidable cause. Missing financial statements, outdated SSM documents, or absent tax filings frequently stall an application before it is properly assessed.
We review your profile against each of these before submitting, and advise on what to strengthen first if something needs work.
What We Help Finance

Working capital
Bridging cash flow gaps and funding day-to-day operations, particularly for businesses with long receivable cycles.

Business expansion
New premises, additional locations, or scaling operations.

Commercial property
Purchasing or refinancing business premises

Trade financing
Letters of credit, invoice financing and trade facilities for businesses dealing with import, export or long payment terms.

Asset and equipment purchase
Machinery, commercial vehicles and equipment financing.
Documents Checklist
- Form 9, 24 and 49
- Audited financial statements for the latest two years
- Directors' personal financial documents
- Two years of Borang B with tax receipts
- Personal bank statements
- Partnership agreement where applicable
Not sure which category applies to you, or missing some of these documents? Send us what you have and we will tell you what else is needed.
Frequently Asked Questions
Talk to Us About Your Business Financing
Send us your business details and we will tell you honestly which lenders are realistic for your profile — and what to strengthen first if anything needs work.
 WhatsApp Us

Head Office
Phone
Copyright 2026 © MET Advisory Malaysia Sdn. Bhd.
Disclaimer: The content on this website is provided for general informational and educational purposes only. It does not constitute financial, credit, legal, or professional advice, and should not be relied upon as a recommendation to take any specific financial or credit action. This information has been prepared without taking into account your individual objectives, financial situation, or needs. Nothing on this site is a substitute for professional advice tailored to your specific circumstances. You are solely responsible for conducting your own due diligence before making any financial or credit decision. We recommend consulting a licensed financial advisor, licensed credit provider, or other appropriately qualified professional before acting on any information found on this website. We make reasonable efforts to ensure the accuracy of the content on this site but make no representation or warranty, express or implied, as to its accuracy, completeness, or currency. Information may change without notice and may become outdated. To the fullest extent permitted by law, MET Advisory Malaysia Sdn Bhd and its owners, employees, and contributors accept no liability for any loss, damage, or expense — direct, indirect, or consequential — arising from your use of, or reliance on, any information on this website, or from any decision made based on it. Any links to third-party websites, products, or services are provided for convenience only and do not imply endorsement. We are not responsible for the content or practices of any third party referenced or linked on this site. By using this website, you acknowledge that any decisions made based on its content are made entirely at your own risk.