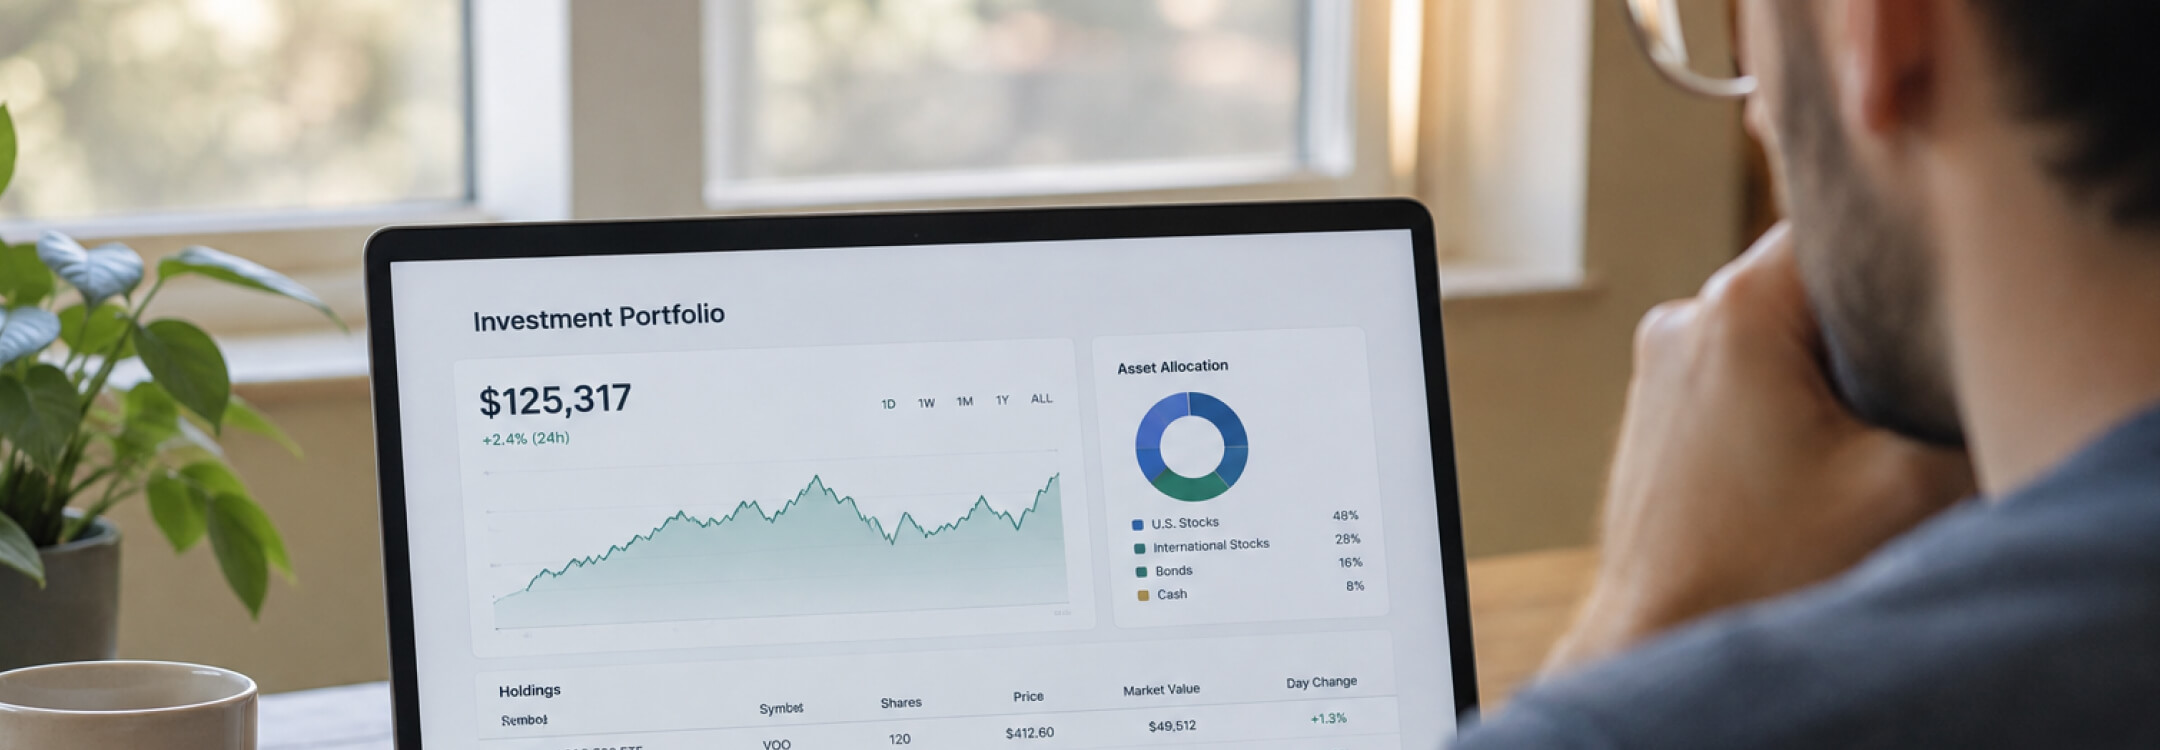
"Wealth management" sounds like something for people who already have money to spare — a service for the comfortable, not the person still building things up. That impression keeps a lot of people from ever having the conversation, and it's the wrong impression.
The truth is closer to the opposite. The earlier a structure is in place, the more time it has to work. Waiting until there's "enough" to justify it usually means waiting through the exact years when starting would have mattered most.
Here's what wealth management actually involves, what doing nothing genuinely costs, and what it realistically takes to begin.
What Wealth Management Actually Means
It isn't a single product, and it isn't stock-picking. It's the coordinated planning of everything you hold and everything you're working toward — savings, investments, protection, and long-term goals — structured so the pieces support each other instead of sitting in isolation.
In practice, that means understanding what you're planning for, when you'll need the money, how much volatility you can genuinely tolerate, and what happens to your family if something goes wrong. The specific products — unit trusts, fixed deposits, insurance, whatever fits — come after that, not before it.
The Myth That Keeps People Waiting
There's no minimum net worth that makes wealth management relevant. What matters is having a clear structure and contributing to it consistently — a modest amount managed properly, started early, tends to outperform a larger amount managed carelessly, started late.
The more useful question isn't "do I have enough to start," it's "what is doing nothing actually costing me." That's a concrete number, and it's usually larger than people expect.
What Idle Money Actually Costs You
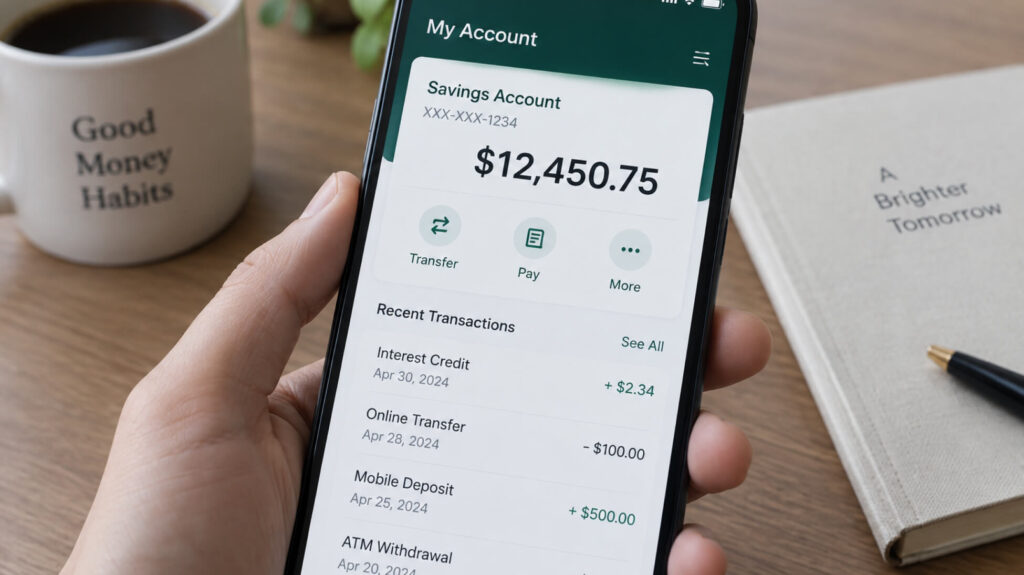
Malaysia's inflation rate has hovered around 4% in recent years. A standard savings account typically pays a fraction of that. The gap between the two is where purchasing power quietly disappears — not through any single bad decision, just through time.
Take RM50,000 sitting in a basic savings account earning 2% a year. After ten years, the account shows RM60,949.72 — growth, on paper. But measured against 4% inflation over the same period, that RM60,949.72 is only worth RM41,175.45 in today's purchasing power. That's a real-terms loss of RM19,774.27 against the balance actually sitting in the account — about 32% of it — even though not a single ringgit was withdrawn.
The balance went up. What it can actually buy went down, by close to a third. That's the entire case for doing something deliberate with idle savings, in one number.
This isn't an argument for taking on large risk. It's an argument for making an active decision about where money sits, rather than defaulting to a savings account because it feels safe. A savings account is not risk-free — it carries the guaranteed risk of losing value in real terms.
The Four Things a Proper Plan Covers
Investment planning
Structuring what you hold against your actual goals and timeline. A five-year goal and a twenty-year goal call for genuinely different approaches — the mistake most people make is applying one approach to both.
Risk management
Protection sized against what you actually stand to lose — income, health, dependants — not an arbitrary policy sold on its own terms. This is where wealth planning and insurance planning overlap, and why they shouldn't be handled as unrelated conversations.
Retirement planning
Projecting what you'll actually need, accounting for inflation over decades rather than years, and identifying the gap between where you are and where you need to be — while there's still time to close it.
Estate coordination
Making sure your wealth plan and your will don't contradict each other. This is a more common gap than most people assume, particularly around EPF and insurance nominations, which pass outside a will entirely.
What It Actually Takes to Start
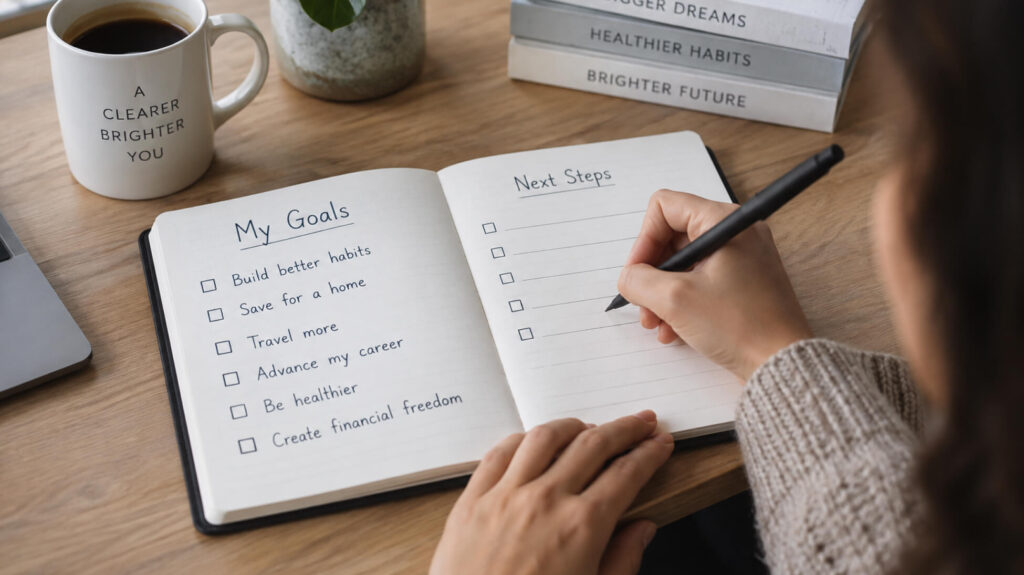
Three things, realistically:
- A clear picture of what you're planning for — not a vague sense of "growing money," but specific goals with rough timelines attached.
- An honest read on risk tolerance — most people overestimate theirs before they've experienced a real decline, which is why this is worth an actual conversation rather than a quick questionnaire.
- Consistency, more than size. A modest, regular contribution started now will typically outperform a larger one started five years from now.
There is no minimum amount required to start the conversation. What there is, is a cost to not having it — and that cost compounds the same way returns do, just in the wrong direction.
Why This Isn't the Same as Asking Your Bank
A bank can only offer its own products, structured around what the bank wants to sell. Independent wealth planning works from the other direction — starting with your situation, then comparing facilities and structures across providers rather than defaulting to whichever one happens to be convenient.
Frequently Asked Questions
Do I need to be wealthy to use wealth management services?
No. This is the most common misconception. What matters is having a clear structure and contributing consistently — the earlier this starts, the more time it has to work. There is no minimum net worth required to have the conversation.
How much money do I need to start?
There's no fixed minimum. Starting with a modest, regular amount and a clear structure typically produces a better outcome than waiting until a larger sum feels more justified — the years spent waiting are years the plan doesn't get to work.
Why does a 4% inflation rate matter so much?
If money grows slower than inflation, it loses real purchasing power even as the balance rises. RM50,000 in a typical savings account at 2% for ten years grows to RM60,949.72 on paper — but against 4% inflation over the same period, that balance is only worth RM41,175.45 in today's money, a real-terms loss of close to a third.
What is risk appetite, and how do I know mine?
It's how much volatility you can tolerate without abandoning your plan partway through. It depends on your time horizon, income stability, and temperament — and most people overestimate it before they've actually experienced a market decline, which is why it's worth discussing properly rather than guessing.
Is wealth management the same as investing?
Investing is one part of it. Wealth management also covers protection, retirement planning, and making sure your estate plan and your investments don't work against each other — it's the coordination between all of these, not any single piece.
Do you charge a fee for wealth management advice?
The initial consultation is free. Any costs tied to specific products are explained transparently before you commit to anything, so you know exactly what you're paying for and why.
Wondering what a plan built around your own numbers would look like?
The first conversation is free, and there's no minimum to start.